
The federal government announced a new tax incentive for entrepreneurs in Budget 2026, rewarding a priority ask from the Canadian tech sector.
Budget 2026 outlines the Canada Growth Incentive, which includes two measures: a new tax exemption on up to $15 million CAD in capital gains earned from successful eligible investments, and an expansion of a capital gains tax rollover for small businesses.
The budget document calls the double-measure “one of the most significant incentives to attract and retain builders here in Canada” because it will encourage founders to build companies, early employees to accept equity, and investors to back Canadian companies.
“This is how you create this circle of investment so that innovators, employees, reinvest.”
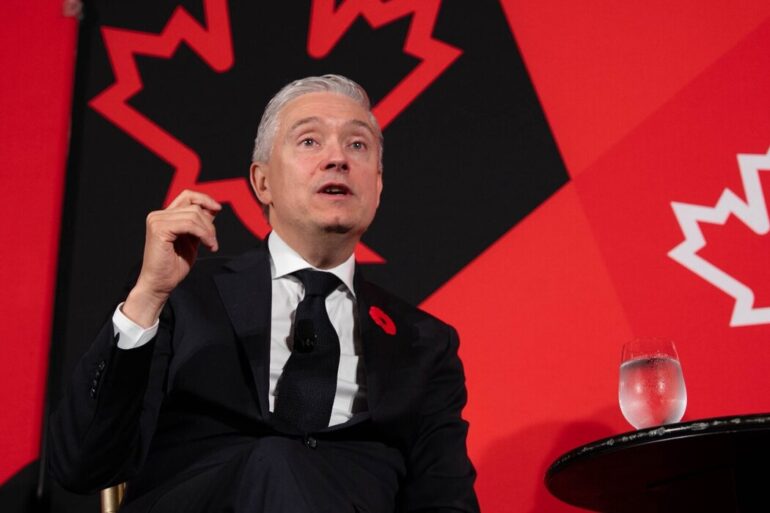
Finance Minister François-Philippe Champagne
“By allowing builders to keep more of the benefits when a business succeeds, these measures will help level the playing field with the United States, encourage more capital to flow to Canadian businesses, and enable successful entrepreneurs to reinvest their proceeds into Canada,” the budget reads.
“We’re gonna be very competitive [for] people who want to grow companies, reinvest in Canadian companies,” Finance Minister François-Philippe Champagne said at a press conference on Thursday.
The changes come after demands from several Canadian tech and investor groups. The Council of Canadian Innovators, the Canadian Venture Capital & Private Equity Association (CVCA), the National Angel Capital Organization (NACO), and other industry associations launched a campaign last month asking the feds to create a tax incentive similar to the US Qualified Small Business Stock (QSBS) regime.
The QSBS rules in the US allow early investors to shield up to 100 percent of their federal capital gains when a company sells, with a value of up to $10 million USD or 10 times the original investment.
Canada’s new exemption would shield up to $15 million CAD of exit value from capital gains taxes. For instance, a founder with a $15-million gain from selling their business would keep nearly 96 percent of that exit value, compared to 71 percent before.
In practice, that means immediately before and after shares are issued, the combined value of the corporation’s assets can’t exceed $100 million. The business must also be a Canadian-controlled private corporation. For at least two years after shares are issued, the company must be “carried on primarily in Canada.” When the shares are sold, the business can be a Canadian-resident corporation that is either private or publicly listed on a stock exchange located in Canada.
Canada’s tech advocates saw the tax changes as a way to de-risk initial investment in Canadian companies—amid a difficult environment for early-stage fundraising—and to make it easier for the eventual profit to be reinvested into other domestic ventures.
The groups involved in “Bet on Canada” welcomed the federal announcement. CVCA CEO Ben Bergen called it an “important step towards rewarding investors who put capital into Canadian companies,” and NACO CEO Claudio Rojas said it was “the strongest signal in a decade that risk-takers and builders at the earliest stages of growth are a national priority.”
“Bet on Canada” also proposed a broader capital gains rollover that would allow more entrepreneurs and investors, including those investing through corporations or funds, to defer capital gains taxes when they reinvest proceeds into another qualifying Canadian business. A small-business rollover currently exists under the Income Tax Act, allowing individuals to defer capital gains taxes when they reinvest proceeds into another eligible small business by the following year.
The feds did not expand on the eligibility of who can use the small business rollover, but did extend the time period to reinvest shares into another Canadian small business. An individual who has realized capital gains will have three years after the year they sold shares to reinvest them in a qualifying Canadian business. There’s also a provision for individuals who enter into simple agreement for future equity (SAFE) agreements—a common investment structure for early-stage startups—where the capital gain could be deferred for another two years.
The “Bet on Canada” campaign noted that the measures should cover sectors like advanced manufacturing and mining. But the new measures exclude companies operating as consultancies, or those in agricultural, fishing, forestry, mining, financial, insurance, utilities, real estate, food and accommodation, arts, recreation, or entertainment sectors.
The new capital gains exemption is immediately coming into effect and is applicable to shares issued before 2037. The expansion of the capital gains rollover will start on Jan. 1, 2027.
The measure represents a complete policy turnaround for the federal Liberals, who, under Prime Minister Justin Trudeau in 2024, butted heads with the tech industry over a controversial capital-gains inclusion rate increase. That measure was axed by then-Prime Minister-designate Mark Carney the evening he won Liberal party leadership.
In Budget 2026, the feds framed the Canada Growth Incentive as a measure to make the country’s tax system more competitive, alongside the previously announced Productivity Mega-Deduction. This measure allows businesses to immediately deduct the full cost of most new capital investments, such as software, computer hardware, and patents.
The government estimates this will result in a $715-million tax revenue drop by 2031. The budget’s annex also says the measure will benefit the founders, early-stage employees, and shareholders in eligible Canadian corporations, over 80 percent of whom would likely have an adjusted gross income of more than $200,000.
In response to media questions about how this tax break for tech squares with the federal government’s affordability focus, Minister Champagne said he was thinking about supporting Canada’s startups.
“If you want to grow, there’s this kind of valley where you have to go to the United States—you cannot find capital here,” Champagne said. He added that the tax incentive was modelled to be competitive with the US QSBS measure.
“This is how you create this circle of investment so that innovators, employees, reinvest,” the minister said. “We want more Shopifys.”
Feature image courtesy Francois-Philippe Champagne via X.