
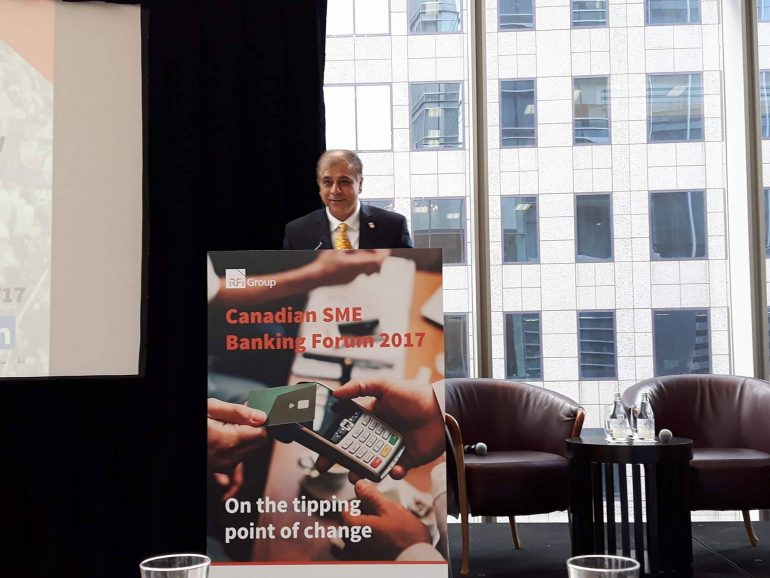
If you ever want to feel out of place, try wearing plaid to a banking conference. That’s initially how I felt when I walked into the beautiful conference space at Toronto’s Shangri-La hotel for the RFi Group Canadian SME (Small-Medium Enterprise) Banking Forum.
Looking at the schedule, one might expect to be in a room full of suits and ties talking about the need to be innovative; a conversation met with elation from some and eye rolls from others. While the suit and tie part was mostly true, something emerged from this event that I was not necessarily expecting – genuine curiosity about tech. The panelists were experts in their field, coming from traditional banking and FinTech spaces, and audience members asked tough questions.
In digital we trust
“Digital is a business strategy, not a distribution channel,” proclaimed opening keynote speaker Rob Frohwein, founder of US-based SME lender Kabbage. Referring to the penchant of traditional banks to see digital only as a new channel to reach a customer while keeping all other manual processes intact, Frohwein warned that any outlook that isn’t digital-first will cause businesses to struggle – or fail – in the near future.
Frohwein explained the four cost buckets that a bank has to work with: cost of capital acquisition, cost of customer acquisition, bad debts, and other expenses like office space and furniture.
“Banks globally serve no sector worse than we do small businesses.” – BMO head of commercial banking and partners
He called upon FinTech startups to take heed that a large bank will always win out on cost of capital acquisition; they have access to billions under management and the Bank of Canada, something no FinTech startup has at this point. However, startups can win in this space when they use technology to lower the other three types of costs, in particular, office and employee maintenance expenses like frequent travel and international taxes.
This is the space where digital-first business mindsets pay dividends as companies are able to remain lean and expand into new markets or geographies around the world from a central hub, like Toronto.
Knowing this, it’s no wonder that the IT sector in Canada contains the highest percentage of high-growth companies, which are companies with more than 10 employees and a growth rate of 20 percent over a three-year period, and “Gazelles,” a subset of high growth companies with sustained growth for up to five years, says Anil Arora, chief statistician for Statistics Canada.
In banks we don’t…kind of
From the Toronto Region Board of Trade (ToR BOT) perspective, CEO Janet De Silva is excited for Toronto’s startup ecosystem, but sees a challenge – ready access to funding. “Canada lacks a robust startup funding program,” she said to the audience as she explained the new mission of the ToR BOT, which is to make Toronto a globally competitive and sought-after business hub.
While the numbers from Arora’s earlier presentation might initially contradict this claim, as only 9.2 percent of SME founders reported access to capital as an obstacle to innovation, De Silva was specifically referring to export-ready Canadian companies who need growth capital to access global markets; only five percent of export-ready SMEs have the capital to reach global markets, she says. Given the amount of capital flowing through the Canadian banking system, it’s easy enough to write off this problem as SMEs simply needing to go to their bank and take a loan.
The reality, to the delight of FinTech founders, is much more complex.
“Banks globally serve no sector worse than we do small businesses,” said Andrew Irvine, head of commercial banking and partners at BMO. Instead, many banks and traditional financial institutions ignore SMEs, as their frameworks are set up to handle complex global transactions or work with high net worth individuals who want – and pay for – high-touch service. This creates an opening for FinTech companies to win the early trust of consumers by offering them a better customer experience or a more intuitive process based in technology.
Better together
VCs, founders, and traditional banks are taking note of the customer-service trend, but it seems that money is now flowing in the direction of FinTech startups and big banks solving the challenge together instead of apart. Shying away from the commonplace tech term of ‘disruption,’ Irvine noted that VCs are investing in FinTech startups whose model is predicated, at least on some level, on partnerships with large financial institutions over the early-FinTech cry of ‘wanting to destroy banks.’
Cato Pastoll, founder and CEO of Lending Loop, a peer-to-peer online lender for SMEs that had to shut down for eight months due to potential OSC violations, cautioned would-be founders from becoming too dependent on partnerships. “You cannot found a company expecting a partnership,” he says, noting that it is far too risky to hinge your entire business on whether an ‘elephant’ will do business with you. “Instead, solve a real problem that will get you going and keep the door open for partnership opportunities.”
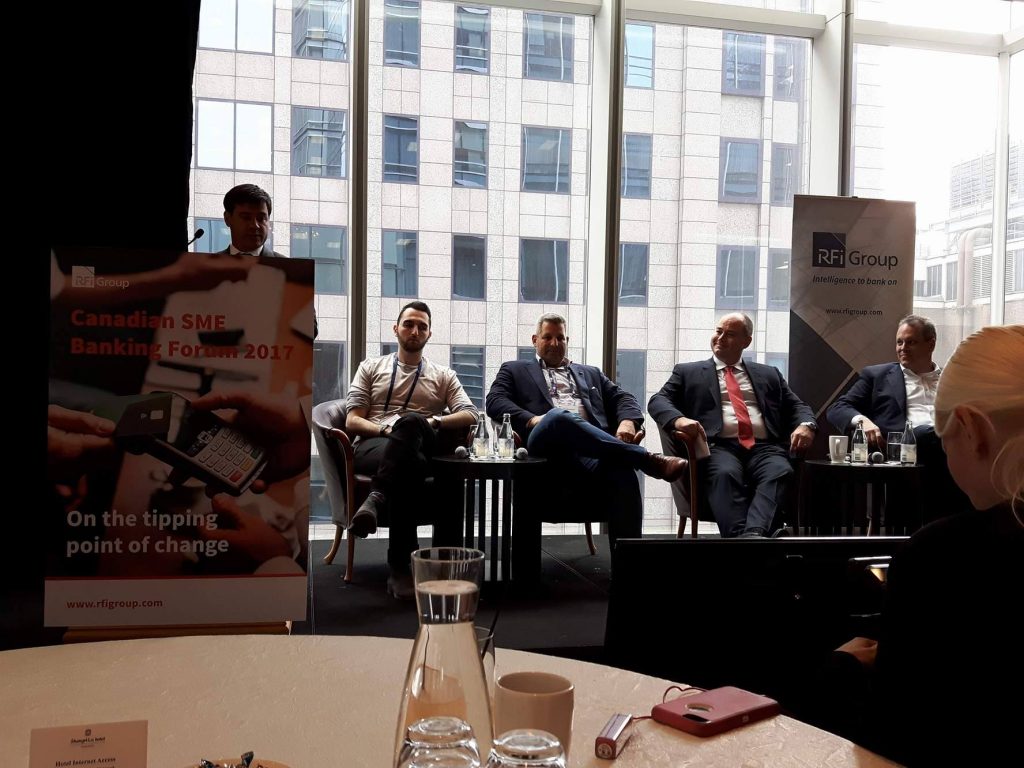
Pastoll also notes that partnerships shouldn’t just be beneficial to organizations, but also customers, a sentiment echoed by Jeff Mitelman, CEO of Thinking Capital. “Typically, partnerships merge a startup’s innovative product with a large bank’s trusted brand or distribution network, both of which make the customer experience greater,” he explained.
Closing out the conversations, a sentiment echoed throughout was the importance of developing new measures of creditworthiness for SMEs, as credit scores and other traditional measures are falling short.
Pastoll noted amazing innovation on the developing world on this subject, where credit scores are unavailable or unreliable. Instead, they use proxy trends like where you go every day (to a workplace?) or your transaction history (do you consistently have money coming in and flowing out?) to judge someone’s creditworthiness. “We’ve been spoiled for data,” Pastoll jokes, a comment seconded by Irvine as he mentioned how traditional banks are treasure troves of data. “We need to develop micro-data points and proxy data points to show someone’s potential.”
From there, the speakers agreed, we can fund significantly more innovative products and businesses that may not have passed traditional screening processes.