
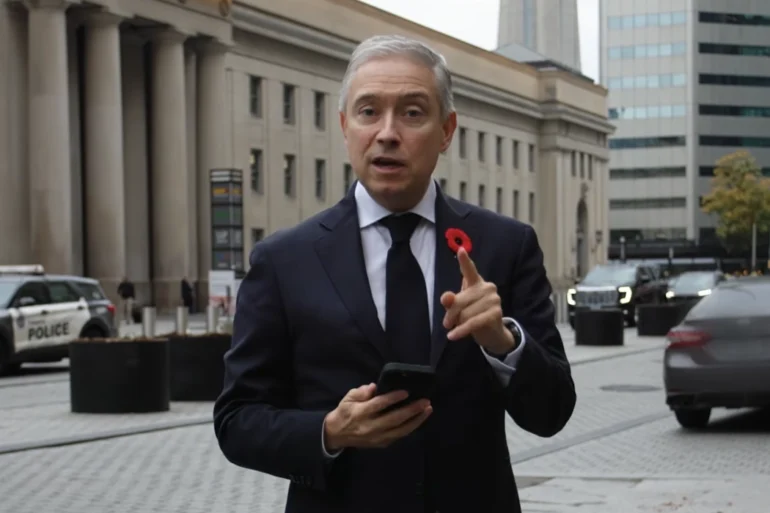
Last week, Canada’s finance minister posted a promotional video to his social media demonstrating Canada’s new real-time payment system, the Real-Time Rail (RTR).
In the video, Minister François-Philippe Champagne uses his smartphone to transfer $250 from a Wealthsimple account to a Koho account for Wainwright Tragedy Appeal, a relief effort led by the Canadian Red Cross. The demo shows a Wealthsimple-branded screen offering the option to send up to $100,000 for free, instantly, by inputting the recipient’s direct deposit details. Champagne clicks ‘Send Money’ and gets a Koho notification instantly, saying the money was deposited.
“Starting today, Canadians can send and receive money in seconds. Any hour, any day, all year round,” Champagne says.
Payments Canada says the RTR launch is a “foundational first step,” and that its phased approach will ensure the system is safe and secure.
However, the use case shown in the video is not yet broadly available to Canadians. While RTR officially launched on Nov. 9, not all of the Phase 1 participants are up and running on the new system.
First, take Champagne’s video. While the demo was a “real, live transfer,” a Wealthsimple spokesperson told BetaKit that type of transfer is currently being beta-tested with Wealthsimple employees, with plans to launch to the broader public in 2027. In an email, Koho said the RTR functionality is not yet widely available to customers because the team is still finalizing testing.
Koho and Wealthsimple (whose vice-president of payments strategy and chief compliance officer, Hanna Zaidi, sits on BetaKit’s board of directors) are not the only companies with users who will have to wait a little longer before getting to properly use RTR, a federal project that for years has held the promise of modernized payments and improved competition. The two are part of a broader list of eight participants in RTR’s first phase, alongside Questrade, DoBusiness.com, Paramount Commerce, Bank of America, Peoples Trust Company, and Digital Commerce Bank. In addition to bringing more of Canada’s financial institutions on board, there’s still work to be done for companies building payment services on top of the new infrastructure.
Questbank, for example, is the banking entity of Questrade Financial Group, which has not yet officially launched. In an email to BetaKit, a Questrade spokesperson said it will share details close to the launch of its consumer banking products.
Peoples Trust Company is participating as a settlement agent (helping settle transactions for entities without a direct settlement account) and said in an email it looked forward to “direct participation” in future phases. Paramount Commerce (which has agreed to be acquired by US company Shift4) said it is actively making real-time payouts with RTR, and Digital Commerce Bank said it was already receiving and sending funds via the payment rail. DoCommerce.com has not responded to a request for comment.
Payments Canada, the non-profit organization responsible for delivering Canada’s payments infrastructure, says the launch is a “foundational first step,” and that its phased approach will ensure the system is safe and secure. It added that since RTR is a payment infrastructure, not a consumer-facing app, “individual financial institutions manage their own customer product timelines and rollouts.”
The Department of Finance has not yet responded to BetaKit’s request for comment.
What is RTR?
The RTR system is an instant, always-on payment infrastructure for Canadians and their financial institutions to transfer funds. It first began development as a payments modernization project in 2015, with a target launch of 2019. Since then, it has been fraught with delays: Payments Canada pushed back the rollout to 2022, then later rescheduled it for mid-2023, and again to 2026, when it finally launched on Nov. 9 with eight initial participants. Notably, the system is meant to allow emergent financial companies to move money for customers without relying on banks or paying them a fee.
In Canada, existing payment infrastructure is limited by speed and transfer size. RTR is meant to support bigger transactions and settle them instantly. When making payments, Canadians typically see money leave their accounts right away, but transactions are actually settled within hours or days, which is why it can take up to three business days for a credit card payment to post.
Since Champagne’s video was posted, many social media users have expressed confusion about how the RTR differs from existing payment systems, like Interac e-Transfer.
While the video depicts a similar system, RTR is different from e-Transfer because it is an infrastructure rail that products and services can be built on. Interac is a delivery partner for RTR, whose backend infrastructure will start clearing and settling Interac’s e-Transfers over its next phases. While Interac’s e-Transfer system is faster than those traditional payment rails, it typically limits consumer transfers to $3,000, and businesses to $25,000, while RTR limits are at $100,000.
“I think the most visible advantages, perhaps, lie more in the small business segment,” Fintechs Canada executive director Adriana Vega told BetaKit last week. “That’s a segment that is super challenged with delayed payments due to batch settlement.”
Right now, only select financial institutions have direct access to Canada’s payment rails, which collectively support 99 percent of daily transactions. This includes Peoples Trust Company, which is the only settlement agent in the first cohort of RTR participants. To send and receive payments via RTR, both parties will need to be onboarded to the new system. That’s why Champagne could use Wealthsimple as the sender and Koho as the recipient in his video demo.
None of Canada’s Big Six banks are participating in this first phase, as BetaKit had previously reported, and some in the industry have criticized the lack of participation, given that these financial institutions process the vast majority of payments in Canada.
Daniel Eberhard, CEO of Koho, told BetaKit last month that a real-time system without widespread adoption would be “performative,” while Vega argued that RTR needs banks’ participation to be a success. Payments Canada has said that all major Canadian financial institutions will join in the coming months, making the RTR available to more than nine in 10 Canadians within its first year.
Despite arriving later than that of other G7 countries, Canada’s RTR was the first to launch with anti-fraud mechanisms built in. With faster payment settlement, that also means funds transferred for nefarious reasons are more difficult to claw back from fraudsters. Interac, which is the exchange solution provider for RTR, has created a central fraud scoring system and a way to confirm that funds are being routed to the correct account.
With files from Alex Riehl.
Feature image courtesy Payments Canada via YouTube.